REMBAUM'S ASSOCIATION ROUNDUP | The Community Association Legal News You Can Use

561-241-4462    |    9121 N. Military Trail, Ste. 200   |   Palm Beach Gardens, FL 33410

Important Information for New and Existing Board Members

EDUCATION REQUIREMENTS

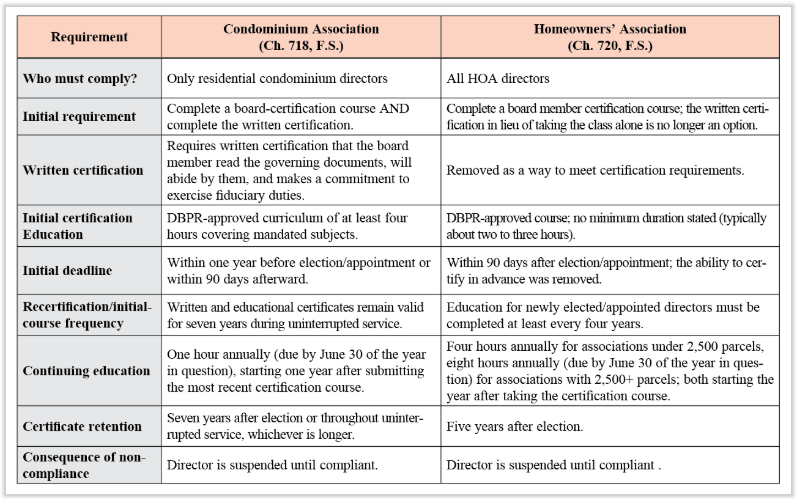
As election season will soon be at hand, it is always a good idea to review both initial certification and continuing board member education requirements. There are significant differences as related to condominium board members as compared to homeowner association board members for both the board certification class and the continuing education requirements, as you can see in the chart below.

Throughout the year Kaye Bender Rembaum P.L. offers free board member certification courses as well as continuing education courses for all attendees on a rotating schedule so that you can enjoy one or more of them from the privacy of your own home. To view the calendar, use your browser to visit KBRLegal.com.
RULES and POLICIES EVERY BOARD SHOULD CONSIDER ADOPTING

If you wait until you actually need any of the types of rules and policies discussed below, then in all likelihood you have waited too long. The purpose of adopting the rules and policies discussed below is to provide for the orderly operation of your association so that your day-to-day activities are not encumbered by one or more cantankerous association members whose sole purpose is to wreak havoc upon the board.

A. OFFICIAL RECORD REQUESTS RULES

The board should consider adopting rules regarding official record requests and where and how such requests must be sent. Absent that, a member could send an email or scribble their request on a napkin and give it to a board member triggering the statutory timeline for a response, which can lead to financial penalties for failure to timely make the requested records available for inspection and copying. Such rules can also take into account the permitted frequency of official record requests from a member as well as maximum time to perform such inspections.

Condominium associations should also consider adopting similar rules regarding written inquiries received from an owner via certified mail as failure to properly respond can lead to the association not being able to collect attorneys’ fees and costs in the event of later litigation that was the subject matter of the written inquiry received via certified mail. Such rules can also take into account that each subpart of a question counts as a separate individual question, thereby providing for a total number of questions, including all subparts, to not exceed 20 in total.

B. BOARD AND MEMBERSHIP MEETING DECORUM RULES

These rules can assist business being conducted in an orderly fashion at meetings and can include, without limitation, when the members have the right to speak, a time limit for owner statements (such as three minutes), and other important conduct provisions. Failure to follow such rules leads to the member being excused from the meeting, pending the circumstances. In addition, these rules can also provide for board member decorum as well.

C. ADOPTION OF A COLLECTIONS POLICY

Essentially, having a standardized collections policy ensures that not only are all owners treated similarly in regard to a delinquency, but also it provides for timely and standardized procedures. Such a policy can provide for such things as sending a reminder letter when an owner is a certain number of days past due (such as 15 days), followed by a continuing instruction to management to send the notice of late assessment if the debt is not paid within 30 days of the first letter. If the owner still has not satisfied their delinquency prior to the expiration of the 30 days of the notice of late assessment, then management is instructed to turn the matter over to the association’s attorney to begin collection/foreclosure proceedings, which are so authorized by the collections policy. Such a policy would also include the appropriate interest rate and late fees to be charged in accordance with the association’s governing documents. 

As a reminder, the Florida legislature enacted requirements not too long ago that the association provide one final 30-day notice to a delinquent member before commencing collection and foreclosure activities. This is referred to as a notice of late assessment (NOLA). Upon request the association’s attorney can prepare detailed instructions and provide draft forms so as to ensure statutory compliance.

COLLECTION and FORECLOSURE ACTIVITIES

Your board is reviewing delinquencies and discovers that certain members are very delinquent with their payment of assessments. The manager is instructed to turn those files over to the association’s law firm to begin collection-related activities. Because the burden of proof is on the association to prove the debtor is delinquent, all supporting information regarding the delinquency should be part of the turnover file given to the attorney, which includes providing the “basis” or “backup,” if you will, to substantiate the monies due to the association. Therefore, typically the association needs to provide the following documentation to its attorney as a part of the collection turnover package to commence collection related activities:

      1. A copy of the debtor’s ledger that goes back to the last zero balance (in other words, the ledger showing the last time the owner was not delinquent).
      2. A copy of the notice of late assessment as required by Florida law (and the affidavit of mailing, if available).
      3. If a special assessment is included on the ledger, then a copy of the meeting notice that was posted and mailed to all of the members at least 14 days in advance, the resulting meeting minutes and the notice that was sent to the membership advising that the special assessment was adopted/passed, and the due dates.
      4. If a fine is included on the ledger, and the declaration permits fines to be converted into an assessment, then all of the backup paperwork must be provided, which would include the notice of board meeting where the fine was considered, a copy of the correspondence sent to the owner at least 14 days prior to the fining committee meeting, the minutes resulting from the fining committee hearing, and a copy of the correspondence sent to the owner thereafter advising them as to the debt owed. In addition, depending on the exact language in the declaration, it may be necessary for the board to actually take official action to convert the fine into an assessment (please note that a fine can only potentially be converted into an assessment for a homeowners’ association governed by Chapter 720, F.S.). It is not always automatic, even if the language might lead the ordinary reader to believe as much, and at times it is still necessary to convert the fine into an actual assessment. With that in mind, it is always a good idea to discuss whether your declaration permits the fine to automatically be treated as an assessment, or if other action is required by the board to do so. And remember, unless the declaration provides the authority for the fine to be treated as an assessment, then it cannot be collected as an assessment. Rather, the association would have to resort to other collection means such as small claims court to collect the fine.

The association’s attorney will be a tremendous resource to the board and will play an integral role with assisting the board in conforming all of the above-discussed rules and regulations and policies to your association.
Rain, Rain…Go Away!

[Nov. 3, 2026] | As I write this, the roads in my neighborhood are flooded. Without a large truck, no one is going anywhere. It has been reported that some areas received extraordinary amounts of rain in only a matter of hours. As far as I know, none of my neighbors’ homes flooded, although I would not be surprised to learn that a few garages took on water.

The finger-pointing and accusations have already started.

Without even a basic understanding of what just happened, some residents are threatening to sue their Association and management company. The frustration is understandable. When your street looks like a river and water is approaching your home, you want an explanation. You want someone to fix it. And, perhaps most naturally, you want someone to blame.

But sometimes the culprit is not the Association, the manager, a clogged drain, or a broken pump.

Sometimes there is simply too much water and nowhere for it to go.

The torrential rains that fell over the last several days wreaked havoc across large portions of Florida. Community after community experienced flooded roads, overwhelmed drainage systems and, in some unfortunate instances, water intrusion into homes.

What many Floridians do not realize is that water standing temporarily in streets, swales, lakes and other designated areas does not necessarily mean the drainage system has failed. Those areas are often components of the storm-water-management system itself.

So, before blaming your community association because the street in front of your house looks more suitable for a kayak than a car, it helps to understand where all that water is supposed to go.

YOUR COMMUNITY’S DRAINAGE SYSTEM DOES NOT EXIST IN A VACUUM

When an extraordinary amount of rain falls in a very short period, the problem is not simply getting water into a storm drain. The problem is what happens to the water after it gets there. That distinction is critical.

Florida’s drainage infrastructure is better understood as a series of interconnected systems. Rain falls on homes, roofs, driveways, sidewalks, parking lots and streets. Some of it soaks into the ground. The remainder becomes storm-water runoff and must be collected, stored, absorbed or conveyed elsewhere.

The Southwest Florida Water Management District explains that storm-water systems are specifically designed to collect and manage that runoff. Depending upon the system, water may enter retention areas, detention ponds, swales, catch basins, underground pipes or other drainage facilities. Retention systems allow water to infiltrate into the ground, while detention systems temporarily store water and release it gradually through an outflow structure.

In other words, that lake behind your house may not be there merely because somebody thought waterfront lots would sell for more money. It may be an important piece of your community’s storm-water infrastructure. Your community’s system is only one piece of a much bigger puzzle.

In South Florida, for example, the South Florida Water Management District describes the regional flood-control system as a primary network of canals and natural waterways connected to community drainage districts and hundreds of smaller neighborhood systems. Accordingly, flood control is a shared responsibility involving the District, counties, municipalities, local drainage districts, homeowners’ associations and residents.

That means the storm drain in front of your house is not necessarily the end of the drainage system. It is closer to the beginning.

Think about what happens after rainwater enters the drain on your street. Water collected within a community may move through catch basins, pipes, swales, ponds, lakes and control structures. Depending on the particular system and its permits, some water may infiltrate into the ground, some may be temporarily stored, and some may ultimately discharge downstream.

Each component has a job. But each component also has a limit. A detention pond, for example, is not intended to empty instantaneously. The Southwest Florida Water Management District explains that after a storm, water in a detention pond slowly drains through the pipe in its outflow structure.

There is good reason for that controlled release. Imagine what would happen if every subdivision, shopping center and development could immediately dump all of its storm-water downstream at the same time. The downstream system would have to receive all of it at once.

So, storm-water management is not simply about moving water away from your property as quickly as humanly possible. It is also about storing water, controlling its release, allowing infiltration where appropriate, and managing the rate at which runoff enters downstream systems.

Think about draining a swimming pool. If your swimming pool has one outfall pipe, emptying the pool may take a considerable amount of time. Add several identical pipes with somewhere for the water to go and, naturally, the pool can drain considerably faster.

But now imagine that every home in your neighborhood begins draining its swimming pool at exactly the same time. Then imagine every community surrounding your community does the same thing. Then imagine that the canal, lake, reservoir or other receiving system into which all those pipes ultimately discharge is already full. It no longer matters very much how large your individual drainpipe is. The water has nowhere to go.

That is essentially the problem drainage systems confront during extreme rainfall events. Your neighborhood may be capable of moving water perfectly well under ordinary circumstances. Its storm drains may be clear. Its pipes may be unobstructed. Its lakes may be properly maintained. Its control structures may operate exactly as designed.

But your system still depends upon conditions beyond the boundary of your community. If the downstream receiving system is already carrying tremendous volumes of water, your community cannot simply command its water to disappear.

WHY DOESN’T THE ASSOCIATION JUST PUMP THE WATER OUT?

This is the question that inevitably comes next.

“If the lake is too high, why doesn’t the Association just pump it down?” Pump it where? That is the question. Moving water from Point A accomplishes very little if Point B is already overwhelmed.

If every community responded to a regional flood by indiscriminately pumping its water into the downstream system as quickly as possible, it could simply transfer the problem from one property to another. In addition, storm-water facilities operate under permits and engineered designs governing how water is collected, detained and discharged. The answer ordinarily is not for a homeowners’ association to unilaterally redesign or operate its storm-water system in whatever manner produces the fastest removal of water.

The objective is to manage the water through the system for which the community was designed and permitted.

WHEN EVERYTHING FILLS UP AT ONCE

Here is where Florida’s geography and development become particularly important. As land is developed, natural surfaces are replaced by roofs, roads, sidewalks, driveways and parking lots. Those surfaces do not absorb rainfall the way undeveloped land does.

The South Florida Water Management District explains that urbanization disturbs natural water flow because impervious surfaces reduce the amount of rain that infiltrates into the ground. The resulting increase in runoff volume can overload drainage systems.

That is the heart of the issue. A drainage system has finite storage and conveyance capacity. The community lake has finite storage. The pipes have finite capacity. The control structure has finite discharge capacity. The downstream canal has finite capacity. Wherever the water ultimately goes has physical limits as well.

Extreme rainfall can therefore produce a cascading problem. Water is arriving faster than portions of the drainage network can store, infiltrate or convey it. Once downstream water levels rise sufficiently, drainage upstream necessarily becomes more difficult.

Picture a line of funnels emptying into one another. Everything works beautifully while the bottom funnel can discharge water faster than the funnels above are supplying it. But once the bottom fills, water begins backing up through the system. Making the first funnel bigger does not solve the problem. The bottleneck is downstream.

That concept helps explain one of the most frustrating observations after an extreme storm: the rain may have stopped, but the street is still flooded.

If there is insufficient downstream capacity, drainage takes time. Water has to move through the interconnected system, water levels must fall, ponds and canals must recover storage capacity, and saturated ground may have to absorb or release water.

THEN WHY ARE THE ROADS UNDERWATER?

Because in many storm-water designs, temporary flooding of lower-lying areas can provide storage before water reaches buildings. That may sound crazy to the person looking outside and seeing two feet of water where yesterday there was asphalt, but consider the alternative.

When an extreme storm produces more water than can immediately leave a community, the water has to occupy some space. Between temporarily occupying a street and entering someone’s living room, which would you prefer?

The fact that streets or other low areas are holding water while homes remain dry may therefore tell a very different story from the one residents initially assume. It does not automatically prove that the drainage system failed.

Depending upon the property’s approved storm-water design, temporary storage may be part of how the system protects buildings during unusually severe rainfall.

That said, prolonged or recurring flooding should never simply be dismissed as “normal.” It may warrant review by the appropriate engineer to determine whether drains are obstructed, pipes have failed, elevations or grading have changed, ponds have lost storage capacity, control structures are operating properly, or the system is otherwise functioning according to its permitted design. Maintenance matters.

The Southwest Florida Water Management District recommends routine inspection and maintenance of storm-water infrastructure, including inspection of outfall structures, discharge pipes, inlets, outlets and catch basins, particularly following major storms.

But there is an enormous difference between a drainage system that floods because it has not been properly maintained and a properly functioning drainage system that is temporarily overwhelmed by an extraordinary volume of water. Those two situations should not be confused.

Remember, much of Florida was historically wetlands, marshes and other low-lying land, and living here means accepting that water will always be part of the equation. If you own property in Florida and choose to go without flood insurance, you may as well take a trip to Las Vegas, put your money on the table and roll the dice. And do not make the mistake of believing that because your home is outside a designated high-risk flood zone, you are somehow safe from flooding. FEMA’s current data shows that nearly one-third of National Flood Insurance Program claims from 2014 through 2024 came from outside high-risk flood areas. Most homeowners’ insurance policies do not cover flood damage.

In Florida, particularly after watching fifteen inches of rain fall in a matter of hours, gambling that the water will stop at the flood-zone line may be one bet you simply cannot afford to lose.

With all of the above in mind, before you go pointing fingers at your board of directors, consider pointing them at your legislators instead. If your community experienced flooding and have additional concerns, please be sure to contact your association’s legal counsel.

When Directors’ and Officers’ Insurance Isn’t What You Think It Is

When Directors’ and Officers’ Insurance Isn’t What You Think It Is | A Wake-up Call for Community Association Board Members

Over the last several months, I have encountered several situations in which condominium and homeowners’ association board members were shocked to learn the true nature of the directors’ and officers’ liability coverage they believed was designed to protect them. In each case volunteer board members were named individually in lawsuits filed by dissatisfied owners. Little did they know that after the claims were made, they discovered that the policy they had relied upon did not provide the broad protection they assumed existed.

These board members believed they had purchased traditional directors’ and officers’ liability insurance. Instead, they learned that the policy functioned more like a limited legal defense program than a comprehensive liability policy. The distinction can be significant. When a board member is sued, the expectation is often that the insurance company will not only provide a legal defense but may also cover litigation-related expenses and, when appropriate, pay settlements or judgments. Yet many policies contain extensive limitations, exclusions, conditions, and reimbursement obligations that can dramatically restrict coverage.

The lesson for every community association board is simple: Do not assume your insurance coverage provides protection simply because of the insurance declaration page, which sets out the policy limits. Board members have a fiduciary obligation to understand the scope of the association’s insurance program, particularly the exclusions that may eliminate coverage when it is needed most.

Too often volunteer board members believe insurance matters are being handled by someone else. Some assume their management company has reviewed the coverage. Others assume the association attorney has already analyzed the policy. While managers and attorneys can certainly provide valuable assistance, the responsibility for understanding the association’s insurance program ultimately rests with the board itself.

One recent example is a policy issued by a well-known legal defense insurance company. The policy expressly provides that it is a legal expense policy and not a traditional liability policy. According to the policy language, coverage is triggered only when a claim is made against the insured and the association’s existing insurance coverage has been denied or determined not to apply. The clear language of the policy further established that it does not indemnify the insured for money damages, judgments, or other damages that may be awarded in the lawsuit.

In addition, the policy provided the following:

      • The insurer selects the attorney, not the board.
      • Coverage is limited to a maximum of three claims or lawsuits during a 12-month policy period. (This limitation can be quite problematic during complicated association litigation when multiple members sue.)
      • Coverage is only available after required underlying insurance policies have first been notified and have denied coverage and such denial of notice is provided within a set period of days. (Therefore, even if coverage would otherwise be afforded, if there is a delay in providing the notice of denial from other insurance carriers, the claim can be denied!)

Only a review of the actual insurance policy at issue will determine the extent of the coverage provided. Under many such policies’ limitations and exclusions section, the insureds (meaning either the association and/or the actual board members named in the litigation) remain responsible for numerous litigation expenses. The bare bones “director and officer liability policies” being sold may exclude the following:

      • Expert witness fees and costs
      • Deposition fees and costs
      • Paralegal costs
      • Copies and fax charges
      • Legal research costs
      • Travel expenses within Florida
      • Telephone and long-distance charges
      • Data processing charges
      • Standard U.S. mail postage
      • Transcript costs
      • Court reporter fees
      • Attorney travel expenses outside Florida
      • Trial exhibits
      • Expert witness and nonexpert witness fees
      • Overnight delivery charges
      • Surveillance expenses
      • Investigator fees
      • Service of process fees
      • Court fees and court costs
      • Messenger fees
      • Appeal-related expenses
      • All other litigation-related expenses not specifically assumed by the insurer in the policy.

The policy may even provide that if the insurer advances certain costs, then those amounts may be required to be reimbursed by the insured within 30 days. Failure to reimburse such expenses may result in the insurer ceasing payment of further legal fees associated with the claim! For many associations these expenses can become substantial, particularly in complex litigation requiring expert testimony, extensive discovery, or appeals.

Policy Exclusions Every Board Member Should Understand

Director and officer liability insurance policies can contain numerous exclusions which limit when a defense will be provided. Following are examples:

      • Claims or lawsuits that occurred before the policy’s effective date
      • Lawsuits filed outside the State of Florida
      • Claims not timely reported to the insurer
      • Appellate proceedings and appeals
      • Class action lawsuits
      • Federal court lawsuits, except limited categories involving service animals, emotional support animals, housing discrimination, or Americans with Disabilities Act compliance
      • Claims arising after the policy expiration date
      • Cases in which the insured is the plaintiff
      • Post-judgment proceeding
      • Fair Debt Collection Practices Act claims
      • Claims involving properties not listed as scheduled locations
      • Workers’ compensation-related claims
      • Disability benefit claims
      • ERISA-related (Employee Retirement Income Security Act) claims
      • Unemployment compensation claims
      • Intellectual property disputes involving copyrights, patents, trademarks, trade secrets, or trade dress
      • Environmental damage claims
      • Claims in which the insured employs its own attorney to handle the defense, subject to limited exceptions
      • Claims against current or former board members where the association has sued that board member
      • Claims involving pollution-related allegations
      • Lawsuits between current and former board members suing each other vs. the association suing a former board member
      • Lawsuits where the association is suing its own board members
      • Claims not first reported to underlying insurance carriers in accordance with those policies
      • Claims where the insured declines representation by the insurer’s designated attorney
      • Certain lawsuits between master associations and sub-associations
      • Certain lawsuits between sub-associations
      • Claims exceeding the policy’s three-claim annual limitation
      • Claims involving injuries or deaths arising from specified boating and water-sport activities.

When read together, these exclusions significantly narrow the circumstances under which coverage may be available.

Conditions, Reporting Requirements, and Timely Notice Requirements Can Be Just As Important As Exclusions

One of the most overlooked aspects of insurance policies is that conditions can effectively eliminate coverage even when the claim itself appears covered. For example, a policy may require the following:

      • Existing general liability insurance coverage to remain in force
      • Claims to be reported first to the association’s underlying insurance carriers
      • Written denial letters from those carriers within a specific time period
      • Reporting of those denials to the legal defense insurer within specified time periods
      • Submission of lawsuits within designated reporting deadlines
      • Full cooperation with the appointed attorney.

Failure to satisfy any of these requirements could potentially prevent coverage from being afforded at all. For that reason boards should review not only the exclusions section of every policy but also the conditions, reporting requirements, and notice provisions.

The Danger of Assumptions

The greatest risk facing many boards is assuming coverage exists without reading the policy. Every insurance policy contains exclusions, but are such exclusions reasonable? In light of the exclusions, does the association have proper insurance coverage? At the end of the day, the responsibility for understanding the association’s insurance program ultimately rests with the board itself.

Board members owe fiduciary duties to the community they serve. Part of fulfilling those duties includes developing a working understanding of the association’s insurance protections and limitations. A declaration page and premium invoice tell only a small part of the story. Only the policy itself will set out the exclusions, conditions, endorsements, limitations, and definitions that often determine whether coverage actually exists when a claim arises.

A Final Reminder

Every condominium and homeowners’ association board should schedule a meeting with its insurance agent at least annually. Do not, as so many boards do, just accept whatever policy is being sold. When is the last time your insurance agent asked to meet with the board? When is the last time your board received a detailed review of the insurance coverage provided and their exclusions?

During a meeting with the association’s insurance agent, the board should carefully review not only its directors’ and officers’ coverage but also every insurance policy maintained by the association. Ask what is covered. Ask what is excluded. Ask what conditions must be satisfied before coverage applies. Ask whether endorsements have modified the policy language.

The importance of this review cannot be overstated. Not long ago another community association was stunned to learn that it had no coverage for a significant water loss because prior claims had resulted in a water-damage exclusion being added to its policy. When another casualty event occurred and water migrated throughout a multi-story building, the board discovered there was no insurance coverage for the resulting damage. The exclusion was there all along, but no one had reviewed it. In all likelihood that gap in coverage could have been filled by another insurance provider. But after the casualty occurs, it is far too late.

Insurance policies are contracts. The protection they provide is determined not by assumptions but by the words written on the page. A board that takes the time to understand those words before a claim occurs will be far better prepared than the board that waits until after a lawsuit, casualty loss, or coverage denial arrives. An annual policy review with the association’s insurance agent is not merely a best practice. In today’s increasingly complex insurance environment, it is an essential part of responsible community governance. Remember to also consider inviting the association’s attorney to the meeting with the insurance agent because often your attorney’s expertise will focus on additional inquiry and thereby make the time spent with the insurance agent more worthwhile.

Importance of Having Strong Financial Controls and Policies

Florida’s community associations operate as complex financial and administrative organizations responsible for managing significant budgets, often in the millions of dollars; maintaining shared property; and protecting the financial interests of the owners. With this responsibility comes a board’s fiduciary duty to ensure that financial operations are transparent, accountable, and safeguarded against misuse. In today’s environment where associations face rising costs, increased owner scrutiny, and growing exposure to fraud risks, the need for strong financial policies and controls has never been more important. These four tools form the foundation of responsible financial governance:

i.   A fraud response plan
ii.  A refundable deposit return policy
iii. A conservative reserve investment policy
iv.
Internal control procedures that guide how the association handles money, assets, and decision-making.

These tools are not merely administrative “housekeeping” items; they are essential safeguards that protect the association’s finances, support the board’s fiduciary obligations, and reinforce trust within the community.

i. Fraud prevention (and a proper response to fraud) must be a priority for every association because community associations are uniquely vulnerable due to volunteer leadership, limited staff, and trust-based relationships. Fraud can occur through misappropriation of funds, falsified invoices, vendor “kickbacks,” unauthorized reimbursements, theft of refundable deposits, or manipulation of financial records. A good fraud response plan includes an established, structured, and disciplined approach for responding to suspicious activity. It should begin with a clear statement of purpose, such as the following: “The association treats any suspicion of fraud or any suspected misappropriation of assets seriously, and all instances will be reviewed by the board of directors or others, if necessary.” This sets the tone for a culture of accountability and ensures that concerns are not dismissed or ignored.

A strong fraud response plan ensures that employees know exactly what to do when they observe something unusual. The plan instructs staff to immediately document their concerns in writing, including dates, times, discussions, and any supporting evidence. This protects both the employee and the association by creating a clear record of events. The plan also establishes boundaries by instructing employees not to confront suspected individuals, not to discuss allegations with unauthorized third parties outside the association, and not to conduct their own investigations. These safeguards prevent the mishandling of evidence, reduce liability, and ensure that the board and legal counsel maintain control of the investigative process. Property managers are given a defined role as well. They must listen carefully to concerns, preserve evidence, and escalate the matter to the board instead of attempting to investigate on their own without clear authority and parameters established by the board. A fraud response plan is not simply a procedural document; it is a critical internal control that protects the association from financial loss, protects employees from retaliation, and protects the board from claims of negligence or mishandling.

ii. Refundable deposits are another area where associations must have clear procedures. Many Florida associations collect refundable deposits for tenant/leasing issues, move-ins, move-outs, and unit alterations. These deposits are intended to protect the association from damage to common elements or violations of construction rules. However, without a formal policy, associations risk losing track of deposits, failing to return them in a timely manner, or violating the applicable Florida Statutes concerning return of deposits. A comprehensive, refundable deposit return policy establishes clear procedures for determining when a deposit is refundable, how notice must be provided, how long the payer has to claim the funds, and what happens to the funds if they remain unclaimed. For instance, if a deposit is collected by the association in connection with a lease of a condominium unit, the association must ensure its policies strictly adhere to the requirements of section 83.49(3), F.S., as it relates to making a formal claim upon the deposit if damage occurs, as well as the required timing to return a deposit if no claim is being made.

iii. A conservative reserve investment policy is a critical component of an association’s overall financial governance and fiduciary responsibility.

A conservative reserve investment policy—typically emphasizing preservation of principal, liquidity, and minimal risk (e.g., federally insured accounts, treasury instruments, and similarly stable vehicles)—aligns with the board’s fiduciary duty to safeguard association assets. Reserve funds function as the association’s financial safety net, designed to cover substantial, non-recurring expenditures such as roof replacements, elevator overhauls, and structural repairs. Because these obligations are often predictable in timing but significant in amount, exposing reserve funds to market volatility or speculative investment strategies can undermine the association’s ability to meet its statutory and operational obligations when they come due and could even lead to claims of breach of fiduciary duty.

Equally important, a conservative reserve investment policy mitigates the risk of special assessments and financial shock to unit owners. If reserve funds are diminished due to investment losses, the association may be forced to levy substantial special assessments to fund required repairs, creating immediate financial burdens for owners and potential collection issues for the association. Maintaining conservatively invested reserves contributes to the long-term stability and marketability of units/homes. Well-funded and properly managed reserves are widely viewed as an indicator of sound governance, which can positively affect property values, lender confidence, and purchaser demand. Conversely, underfunded or poorly managed reserves—especially if tied to investment losses—can lead to deferred maintenance, diminished property conditions, and reputational harm to the community. In sum, a conservative reserve investment policy is not merely a financial preference; it is a legally grounded risk-management strategy that protects the association and its members.

iv. Internal control procedures are the systems and procedures that prevent fraud, ensure accuracy, and promote accountability. Such internal controls can include the following:

    • The fixed asset capitalization policy
    • The conflict of interest disclosure statement

The fixed asset capitalization policy ensures that capital expenditures are properly categorized and accounted for. It clarifies the difference between repairs and improvements for accounting purposes. For example, repairing a roof leak with modern materials may be considered an “improvement” for accounting purposes, but a “repair” for legal purposes. This distinction matters because misclassification can distort financial statements, reserve studies, and budget planning.

The conflict of interest disclosure statement is another essential internal control. Generally, a rebuttable presumption of a conflict exists if a director or officer (or family member of a director or officer) enters into a contract with the association or has a financial interest in a business that does. A conflict of interest disclosure policy ensures transparency and protects the board from allegations of self-dealing. Together with the fraud response plan and the refundable deposit return policy, these internal controls create a comprehensive system of checks and balances that strengthen financial oversight and reduce risk.

Florida’s community associations face increasing financial pressures and heightened expectations for transparency and accountability. Policies are only effective if they are properly adopted and communicated. A comprehensive fraud response plan, a well-structured refundable deposit return policy, a conservative reserve investment policy, and strong internal control procedures are essential tools for meeting these challenges. These policies reduce the risk of fraud, ensure compliance with Florida law, promote fairness and transparency, strengthen financial reporting, and help protect the board and the association from liability. By adopting and consistently applying these policies, associations create a culture of integrity and trust along with a financially healthy community.

If you have questions regarding these financial policies, please reach out to your association’s attorney and/or a qualified and licensed CPA experienced in such matters and in what are referred to in accounting terms as “common interest realty associations” (a/k/a CIRA).

Corporate Transparency Act Compliance and How to File Your Association’s Report

Corporate Transparency Act Compliance and How to File Your Association's Report

The Corporate Transparency Act (“CTA”) was enacted in 2021. The CTA requires that on or before January 1, 2025, all cooperatives, condominiums and homeowner’s associations (collectively, “Associations”) are required to file certain information with the US Treasury department, Financial Crimes Enforcement Network (“FinCEN”). This law requires businesses that are registered with their state’s division of corporations, which includes Community Associations, to provide information on its ‘Beneficial Owners’ which are the decision makers, meaning board members, and officers (and possibly managers, too). Your Association will need to comply with the registration requirements of the CTA or face significant penalties. In addition, any changes to the board members or officers must be reported by updating the information on FinCEN within 30 days of the change.

1) What is the CTA? The CTA aims to combat illicit activity including tax fraud, money laundering, and financing for terrorism by capturing more ownership information for specific U.S. businesses operating in or accessing the country’s market. Under the new legislation, businesses that meet certain criteria must submit a Beneficial Ownership Information (“BOI”) Report to the U.S. Department of Treasury’s FinCEN, providing details identifying the decision-making individuals for the Association.

2) What information will each Association have to report? An Association will have to report:

    • Its legal name;
    • Any trade names, “doing business as” (d/b/a), or “trading as” (t/a) names;
    • The current street address of its principal place of business if that address is in the United States (for example, company’s headquarters. The company address must be a U.S. street address and cannot be a P.O. box;
    • Its jurisdiction of formation or registration (State of Organization) and the date of formation;
    • Its Taxpayer Information Number; and
    • Any beneficial owner/board member (the decision maker).

3) Who is considered a beneficial owner of an Association? A beneficial owner of the Association is defined as an individual who either directly or indirectly exercises substantial control over the Association company. The Association will have to provide:

    • The individual’s name;
    • Date of birth;
    • Residential address; and
    • A copy of an acceptable identification document such as a passport or U.S. driver’s license.

Individuals who meet one of the following criteria are considered to exercise substantial control over the Association:

    • the individual is a senior officer;
    • the individual has authority to appoint or remove certain officers or a majority of directors of the Association, such as developers of a developer controlled Association;
    • the individual is an important decision-maker; or
    • the individual has any other form of substantial control over the Association.

4) When should an Association file this report? When should our report be updated?

    • An Association created or registered to do business before January 1, 2024, will have until January 1, 2025, to file its initial BOI report.
    • An Association created or registered in 2024 will have 90 calendar days to file after receiving actual or public notice that its creation or registration is effective.
    • An Association created or registered on or after January 1, 2025, will have 30 calendar days to file after receiving actual or public notice that its creation or registration is effective.
    • Importantly, there are continuing registration requirements as well. Anytime there is any change in the beneficial ownership it must be reported to FinCin by updating the BOI report within 30 days of the event. This applies to such events as a mid-year replacement board member or officer and possibly after each year’s annual election, too.

5) Are there any penalties associated with not filing or missing the deadlines?

Yes. As specified in the Corporate Transparency Act, a person who willfully violates the BOI reporting requirements may be subject to civil penalties of up to $500 for each day that the violation continues, plus it is adjusted annually for inflation.

Both individuals and corporate entities can be held liable for willful violations such as a failure to comply with the FinCEN registration requirements. This can also include not only an individual who actually files (or attempts to file) false information with FinCEN, but also anyone who willfully provides the filer with false information to report.

6) Are there third-party service providers to help Associations with filing?

Yes. Associations may use third-party service providers to submit beneficial ownership information reports. Third-party service providers will have the ability to submit the reports via FinCEN’s BOI E-Filing website or an Application Programming Interface (API).

While there are many third-party providers which can be located by doing a simple Google search, at this time we cannot recommend one company over another. Therefore, we are merely sharing the following information which we discovered through our own Google search. Four companies assisting with the CTA filings include:

There are others, too.

We understand that some management companies may also offer this service for an additional fee. Whether to consider using your current management company or a qualified third-party provider is a Board business decision.

Please note that Kaye Bender Rembaum, P.L., will not be performing any FinCen registrations.

7) Can an Association file on its own, without the use of a third-party?

Yes, an Association may file on its own electronically through a secure filing system via FinCEN’s BOI E-Filing website (https://boiefiling.fincen.gov). There is no fee for submitting your BOI to FinCEN. An Association can access the form by going to FinCEN’s BOI E-Filing website (https://boiefiling.fincen.gov) and select “File BOIR.”

However, due to the potential liability exposure to the Association and possibly individuals, we do not recommend that an Association undertake compliance with this act by filing on their own.

8) Are there any efforts undertaken to exempt community associations from the registration requirements?

In July, 2024, the Community Associations Institute (CAI) Board of Trustees approved filing a lawsuit to exempt and protect community associations from burdensome requirements outlined in the Corporate Transparency Act. On October 11, 2024 there was a hearing on CAI’s request for a preliminary injunction against the U.S. Department of Treasury to try and exempt Community Associations from the burdensome reporting requirements of the CTA. A ruling is expected in the next few weeks, but not guaranteed. As such, for now, compliance with the CTA by January 1, 2025 remains required.

2024 Legislative Clarifications for Board Members and Managers – An Update

2024 Legislative Clarifications For Board Members and Managers

The purpose of this article is to address the following:

    • Homeowners’ and condominium association board member certification requirements, certificate retention and continuing education requirements (all of which are quite different);
    • Condominium association and homeowners’ association hurricane protection requirements;
    • Clarify homeowners’ association website posting requirements and remind homeowners’ association board members of mandates from the 2024 legislation.

Chapter 718, F.S.: CONDOMINIUM ASSOCIATION BOARD MEMBER CERTIFICATION REQUIREMENTS, CERTIFICATE RETENTION AND CONTINUING EDUCATION REQUIREMENTS:

    • Each newly elected or appointed board member must submit to the secretary of the association the: (i) written certification AND (ii) educational certificate within 1 year before being elected or appointed or 90 days after the date of election or appointment.
    • Specifically, for the (i) written certification, all residential condominium board members must certify, in writing to the secretary of the association, that he or she has read the association’s declaration of condominium, articles of incorporation, bylaws, and current written policies; that he or she will work to uphold such documents and policies to the best of his or her ability; and that he or she will faithfully discharge his or her fiduciary responsibility to the association’s members.
    • For the (ii) educational certificate, condominium association board members must complete an educational curriculum that has been approved by the DBPR that is at least four hours long with certain mandated subjects.
    • A director of an association of a residential condominium who was elected or appointed before July 1, 2024, must comply with both written certification AND educational certificate requirements by June 30, 2025.
    • To reiterate, a director of an association of a residential condominium who was elected or appointed after July 1, 2024, must comply with both the written certification AND educational certificate requirement within 90 days after being elected or appointed to the board.
    • The written certification and/or educational certificate is valid for seven years after the date of issuance and does not have to be resubmitted as long as the director serves on the board without interruption during the seven-year period.
    • Continuing Education: In addition to the (i) written certification and (ii) educational certificate discussed above, one year after submission of the most recent written certification and educational certificate, and annually thereafter, a board member of an association of a residential condominium must submit to the secretary of the association a certificate of having satisfactorily completed at least one hour of continuing education administered by the division, or a division-approved condominium education provider, relating to any recent changes to this chapter and the related administrative rules during the past year.
    • Condominium association board members elected or appointed before July 1, 2024, have until June 30, 2025, to meet the new education curriculum requirement consisting of 1 hour of continuing education per year.
    • The condominium association must retain a director’s written certification and/or educational certificate for inspection by the members for seven years after a director’s election or the duration of the director’s uninterrupted tenure, whichever is longer.
    • Any director who fails to timely comply with the foregoing written certification and educational certificate requirements is suspended from service on the board until he or she complies.

Chapter 720, F.S.: HOMEOWNERS’ ASSOCIATION BOARD MEMBER CERTIFICATION REQUIREMENTS, CERTIFICATE RETENTION AND CONTINUING EDUCATION REQUIREMENTS:

    • Homeowners’ association board members elected or appointed to the board on or after July 1, 2024, must take a board certification course within 90-days after being elected or appointed to the board (no minimum time required, typically around two hours).
    • In addition, homeowners’ association board members must complete the education specific to newly elected or appointed directors at least every four years.
    • The DBPR approved educational curriculum specific to newly elected or appointed directors must include training relating to financial literacy and transparency, recordkeeping, levying of fines, and notice and meeting requirements.
    • In addition to the education course specific to newly elected or appointed board members, Homeowners’ association board members with fewer than 2,500 parcels in the association must take four hours of continuing education annually and if 2,500 parcels or more in the association, then eight hours of continuing education annually.
    • The homeowners’ association must retain each director’s written certification or educational certificate for inspection by the members for five years after the director’s election.
    • The ability of a recently elected or appointed homeowners’ association board member to simply submit a written certificate certifying that they read the association’s declaration of covenants, articles of incorporation, bylaws, and current written rules and policies; that he, or she, will work to uphold such documents and policies to the best of his or her ability; and that he, or she, will faithfully discharge his or her fiduciary duties to the association, is no longer an option to meet certification requirements as it has been removed from Section 720.3033, Florida Statutes.

HURRICANE PROTECTION REQUIREMENTS:

    • Chapter 718, F.S.: Condominium Association Hurricane Protection Specifications. Each board of a residential condominium or mixed used condominium must adopt hurricane protection specifications for each building within the condominium operated by the association which may include color, style, and other factors deemed relevant by the board (please note that this provision used to apply to hurricane shutters but now applies to all hurricane protection).
    • Chapter 720, F.S.: Homeowners’ Association Hurricane Protection Specifications. The board or any architectural, construction improvement, or other similar committee of an association must adopt hurricane protection specifications for each structure or other improvement on a parcel governed by the association. The specifications may include the color and style of hurricane protection products and any other factor deemed relevant by the board. All specifications adopted by the board must comply with the applicable building code.

Chapter 720, F.S.: HOMEOWNERS’ ASSOCIATIONS NEW WEBSITE / APP POSTING REQUIREMENTS FOR THOSE HOA’S REQUIRED TO HAVE A WEBSITE / APP:

HOA New Website: By January 1, 2025, an association with 100 or more parcels shall post several documents within its Official Records on its website or make available such documents through an application that can be downloaded on a mobile device.

    • HOA New Website Posting Requirement for Members’ Meetings– Notice of any scheduled meeting of the members and the agenda for the meeting, as required by Section 720.306, Florida Statutes, at least 14 days before such meeting. The notice must be posted in plain view on the homepage of the website or app, or on a separate subpage of the website or app labeled “Notices” which is conspicuously visible and linked from the homepage. The association shall also post on its website or app, any document to be considered and voted on by the members during the meeting, or any document listed on the meeting agenda, at least seven days before the meeting at which such document or information within the document will be considered.
    • HOA New Website Posting Requirement for Board Meetings– Notice of any board meeting, the agenda, and any other document required for such meeting must be posted on the website or app no later than the date required for such notice.

REMEMBER, EVERY HOMEOWNERS’ ASSOCIATION BOARD MUST DO THE FOLLOWING:

    • Adopt hurricane protection standards/rules as discussed above.
    • Provide copies of the rules and covenants to every association member before October 1, 2024, or post same on the association’s website and send notice to each member at their address used for official notices as to where they can locate them.
    • Adopt rules and regulations governing official record retention.

(Written by Jeffrey Rembaum (Kaye Bender Rebaum) and reprinted with permission from the September 2024 edition of the “Florida Community Association Journal“.)

Since When Should the HOA Clubhouse Not Come With Your Home Purchase?

Since When Should the HOA Clubhouse Not Come With Your Home Purchase?

The Florida Legislature Is Called Upon To Act To Put A Stop To Developers Who Require HOA Members To Purchase Their Community Clubhouse And/Or Clubhouse Operations After Turnover

Building property subject to a homeowners’ association (HOA) should not entitle a developer to be in a position to financially gouge the association’s members month after month by using the assessment regime to continually line its pockets. Essentially, that is what association member Gundel argued in court against his association’s developer, Avatar Properties, who built out the Solivita Homeowners’ Association. In this HOA the club facilities, including a spa and fitness center, dining venues, indoor and outdoor pools, parks, tennis courts, and more, were not subjected to the declaration, but rather remained under the exclusive ownership and control of Avatar, the developer, and therefore were not a part of the common areas. This means that as a part of the turnover process, the developer was not required to turn over the club facilities and operations to the now member-controlled HOA but rather retained ownership and control of those facilities. Can you imagine paying hundreds of thousands of dollars for a beautiful new home in a gorgeous community, which includes access to a sprawling clubhouse with dining rooms, spas, and all of the amenities and yet, even though those club amenities are in the middle of the community, they are  owned by a corporation not subject to Chapter 720, Florida Statutes, in any fashion, with the intent being that such club amenities will never be under the control of the HOA’s members?

In the case, Avatar Properties Inc. v. Gundel, Case no. 6D23-170, decided June 22, 2023, by Florida’s Sixth District Court of Appeal, the Court (which, in our opinion, was the correct decision) explained that within the Solivita Declaration, the developer included language for each association member to pay as a part of the annual assessment a sum of money unilaterally determined by the club operator for both club operations and what also was just pure profit as argued by owner Gundel.

The Court explained that the assessment imposed by Avatar (the developer) for the mandatory club membership had two components. One component was the amount required for club expenses to be shared proportionately by each resident. The second component was for a membership fee that represented, according to the Court, an annual profit charge to each owner that was due and payable to Avatar. In fact, if a member did not pay, then their home could even be subject to the lien and foreclosure process by the association.

In the trial court’s summary judgment hearing, the Court ruled in Gundel’s favor, finding that assessments for the club, which constituted profit, were improper because pursuant to Section 720.308 of the Florida Statutes, assessments cannot be levied for profits, but only for expenses.

In response to this case and possibly for other reasons, at least one developer designed a new HOA community with a big difference: it made the clubhouse building and the dirt upon which it was constructed to be a part of the common areas of the HOA. Then through a complicated process laid out in the declaration, the developer provided that the clubhouse operations were not owned by the HOA and that after turnover of control of the HOA to the members, the members must purchase the “operations” of the club at what many consider a grossly inflated price. Should the association members decide not to make the purchase, then the developer maintains the right to sell the club operations to a third party for which the assessment paying members will be at the financial mercy of the club operator forever. No doubt the association membership is already paying for the clubhouse operations through their monthly assessments, and in our opinion to now require the membership to spend millions of dollars to buy those clubhouse operations is just plain wrong!

Let’s break this alternate scheme down. Although previously disclosed in the declaration and its attached club plan, either i) the association membership agrees to purchase the club operations at an inflated price for millions of dollars (and for what—the right to operate their own clubhouse?);  or (ii)  the developer retains the right to sell the club operations to a third party who will then be entitled to charge members assessments to both fund the operations and, like any business, earn a profit for doing what should have been handed over to the membership as a part of the turnover process. After all, what clubhouse operator is going to operate at cost and not expect a profit? Either way, the members lose, lose, and lose.

This type of plan ultimately hurts owners as it will likely create a five figure per member assessment obligation either in the nature of paying back the loan necessary to purchase the clubhouse operations or to be forced to pay a new clubhouse operator. The only money a post-turnover association member should have to pay for their clubhouse operations is the actual money expended for operations (i.e., what it costs to provide the restaurant, spa and pool services, etc.). Common area facilities were never designed or even contemplated to be a continual profit center for a developer or developer-related entity.

Worse still, it appears that these types of schemes have no room for negotiation. The purchase price has been pre-determined by the developer years ago when it initially recorded the community’s governing documents. While the developer can argue it is all disclosed in the governing documents (and therefore proposed buyers/future members have notice of this issue), it takes a fairly sophisticated legal mind to understand how this process is going to work. In this author’s experience, the financial obligations associated with either having to buy the clubhouse and/or the clubhouse operations is often quite a surprise to the members.

In short, requiring the membership to purchase the clubhouse operations based on an unreasonable financial formula requires that the association borrow the millions of dollars necessary to pay the developer. In the end the obligation to pay the loan will be wrapped up in the assessment regime which means, once again just like in the Avatar case, the developer is improperly requiring the association to levy assessments for the developer’s (or third-party club operator’s) gross profit rather than only the legitimate expenses as contemplated by Section 720.308 of the Florida Statutes.

In our opinion, it is evident the Florida legislature needs to protect the citizens of the State of Florida by declaring such schemes unlawful. Clearly, the clubhouse operations should be turned over to the association membership as part of the turnover process, and the membership should not be charged for that which they should already own. If it is the clubhouse structure issue which needs to be purchased because it was not included in the overall purchase price of the houses within the community, then certainly the developer is entitled to recoup its legitimate expenses associated with the buildout; but post turnover the developer should not be entitled to profit at the expense of the association membership. If the developer wants to profit from the clubhouse in the clubhouse operations, then certainly the developer could have included those sums within the purchase price of each member’s home. Their decision not to do so and to artificially deflate the price of a home as a result thereof should not be allowed.

One cannot help but wonder if these types of clubhouse schemes could rise to the level of violating Florida’s Deceptive Trade and Practices Act as set out in Chapter 501, Fla. Stat. In fact section 501.24, Fla. Stat., provides in relevant part that unfair methods of competition, unconscionable acts or practices, and unfair or deceptive acts or practices in the conduct of any trade or commerce are hereby declared unlawful. While the developer can argue that the clubhouse scheme is fully disclosed, it is our opinion the owners can certainly argue that this practice is, at best,  unfair and at worst unconscionable.

Board members and members who live in an association with these types of obligations are strongly urged to discuss their options with competent legal counsel so as to make informed decisions whether to buy the clubhouse and/or the clubhouse operations or consider filing a lawsuit against the association’s developer, arguing as Gundel did in the Avatar case, that this type of profit making activity is unlawful. Also, it must be noted that while the Sixth District Court of Appeal fully agreed with the outcome of the trial court, it certified a question to the Florida Supreme Court regarding the matter. However, the Florida Supreme Court declined review. Therefore, it appears the Gundel opinion remains valid. Nevertheless, it does not go far enough to protect association members from having to purchase their clubhouse and/or clubhouse operations after turnover. Therefore, the Florida legislature needs to do its job and protect the citizens of the state by outlawing this process altogether and requiring an HOA developer to turn over the HOA clubhouse and all of its operations to the association as a part of turnover process.